The Wealth Statement is one of the most important parts of income tax return filing for individuals in Pakistan.
It provides FBR with information about a taxpayer’s financial position, including relevant assets, liabilities, receipts and personal expenses.
More importantly, these figures must make financial sense when compared with the taxpayer’s declared income and previous year’s wealth.
FBR states that completing an online Income Tax Return involves completing the Return of Income and Wealth Statement, and successful submission is confirmed when the relevant forms move from the Draft folder to Completed Task in IRIS.
For many new filers, entering assets is not the most difficult part.
The real challenge is Wealth Reconciliation.
This guide explains the concept step by step.
What Is a Wealth Statement?
A Wealth Statement is essentially a statement of a taxpayer’s assets and liabilities, together with information required to explain changes in wealth during the tax year.
In simple terms, it helps answer questions such as:
What did you own at the end of the year?
What did you owe?
How much did you spend during the year?
Where did increases in your wealth come from?
FBR’s IRIS portal currently provides dedicated Wealth Statement PDF and video help resources for taxpayers.
Wealth Statement vs Income Tax Return
These two documents are closely connected but serve different purposes.
| Income Tax Return | Wealth Statement |
|---|---|
| Reports income for the tax year | Reports financial position/assets and liabilities |
| Calculates taxable income | Helps explain changes in net wealth |
| Includes applicable tax information | Includes assets, liabilities and personal expenses |
| Focuses mainly on income and tax | Focuses mainly on wealth and its reconciliation |
This is why completing the income portion of your return does not necessarily mean your entire filing process is complete.
For the complete filing procedure, read our guide on how to file an income tax return online in Pakistan.
What Information Is Included in a Wealth Statement?
The information depends on the taxpayer’s actual financial circumstances.
IRIS Wealth Statement sections can include information relating to:
- Personal assets
- Liabilities
- Receipts/inflows
- Personal expenses/outflows
- Previous-year net assets
- Current-year net assets
- Wealth reconciliation
FBR’s IRIS guidance specifically provides data-entry areas for Personal Assets / Liabilities / Receipts / Expenses and a separate Reconciliation of Net Assets process.
The figures entered should be based on your actual circumstances and available records.
Step 1: Determine Your Assets
Start by identifying the assets relevant to your financial position at the end of the applicable tax year.
Depending on your circumstances, these may include items such as:
- Cash in hand
- Bank balances
- Residential or commercial property
- Plots or land
- Vehicles
- Investments
- Shares or securities
- Business capital
- Loans or advances given to others
- Other relevant assets
Do not add an asset simply because it appears in an example or another person’s return.
Your Wealth Statement should reflect your own financial circumstances.
At What Value Should Assets Be Declared?
This is an area where taxpayers should be careful.
FBR’s Wealth Statement instructions state that assets in the Wealth Statement are generally reported at cost.
For example, if you purchased an asset in an earlier year, its Wealth Statement treatment should not automatically be changed every year merely because its market price has increased.
However, the current IRIS return may contain additional informational fields or requirements depending on the tax year and asset type.
FBR clarified during Tax Year 2025 that certain market-value information introduced in the return was not used for tax computation or Wealth Statement reconciliation.
Therefore, always follow the fields and instructions applicable to the current IRIS return, rather than relying on an old screenshot or tutorial.
Step 2: Enter Your Liabilities
A liability is generally an amount you owe to another person or institution.
Depending on the facts, examples may include:
- Bank financing
- Outstanding personal loans
- Housing finance
- Vehicle financing
- Other genuine liabilities
Liabilities are important because:
Net Wealth = Assets − Liabilities
For example, owning an asset worth Rs. 5,000,000 does not necessarily mean your net wealth increased by Rs. 5,000,000 if part of the acquisition was genuinely financed through an outstanding liability.
The underlying transaction and liability should be reported correctly according to the applicable IRIS fields.
Step 3: Enter Personal Expenses
Personal expenses are an important part of Wealth Statement reconciliation.
Depending on the taxpayer’s circumstances and the fields available in IRIS, relevant expenditure may include items relating to household and personal spending.
The purpose is not merely to fill boxes.
Expenses help explain how much of the taxpayer’s available resources were consumed during the year rather than accumulated as wealth.
FBR’s current reconciliation structure treats Personal Expenses as part of outflows.
This makes accurate expense reporting important for reconciliation.
Step 4: Identify Other Inflows
Not every increase in wealth necessarily comes from taxable salary or business income.
Depending on the facts and applicable law, IRIS reconciliation may contain separate categories for inflows such as:
- Foreign remittance
- Inheritance
- Gift
- Gain on disposal of assets
- Other legitimate inflows
The current FBR reconciliation guidance specifically shows categories including Foreign Remittance, Inheritance and Gift among possible inflows.
However, simply typing an amount under one of these categories does not prove that the transaction occurred or determine its tax treatment.
Use genuine figures that can be explained and supported if required.
Step 5: Check Previous-Year Wealth
Wealth reconciliation compares your current financial position with your previous financial position.
Therefore, the previous year’s net assets are extremely important.
Suppose your previous Wealth Statement showed:
Net Assets Previous Year = Rs. 2,000,000
and your current Wealth Statement shows:
Net Assets Current Year = Rs. 2,600,000
Your wealth has increased by:
Rs. 600,000
That increase needs to make sense when compared with the inflows and outflows reported for the year.
Step 6: Understand Wealth Reconciliation
This is the core concept.
FBR explains that a Wealth Statement can only be successfully submitted when the increase or decrease between the current year’s wealth and previous year’s wealth corresponds with the difference between relevant income/inflows and expenses/outflows.
In simplified terms:
Increase in Wealth ≈ Inflows − Outflows
The actual IRIS calculation contains specific fields and categories, but this simple formula helps explain the concept.
Practical Wealth Reconciliation Example
Suppose a taxpayer starts the year with:
| Particular | Amount |
|---|---|
| Previous Year Net Wealth | Rs. 2,000,000 |
| Income / Relevant Inflows During Year | Rs. 1,500,000 |
| Personal Expenses / Relevant Outflows | Rs. 900,000 |
| Increase in Wealth | Rs. 600,000 |
| Current Year Net Wealth | Rs. 2,600,000 |
The basic relationship is:
Rs. 1,500,000 inflows − Rs. 900,000 outflows = Rs. 600,000 increase in wealth
And:
Rs. 2,000,000 previous wealth + Rs. 600,000 increase = Rs. 2,600,000 current wealth
The figures therefore reconcile in this simplified example.
This is only an educational illustration. A real IRIS Wealth Statement can contain multiple types of income, receipts, expenses, assets and adjustments.
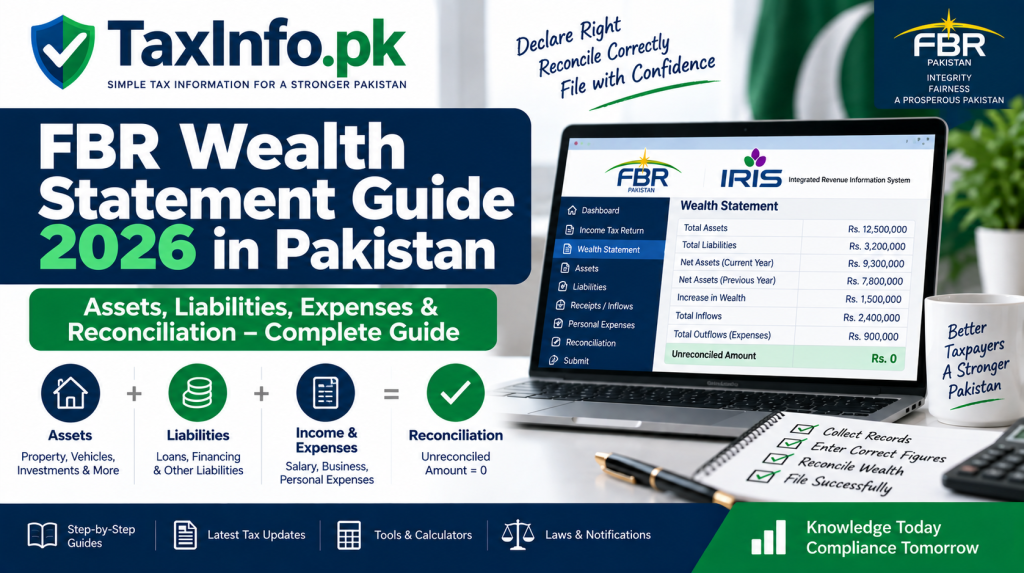
What Does “Unreconciled Amount” Mean in IRIS?
This is a common source of confusion.
FBR’s IRIS guidance explains that the difference between current-year wealth and previous-year wealth must correspond with the difference between inflows and outflows.
When the reconciliation is correct:
Unreconciled Amount = 0
FBR’s IRIS help specifically instructs taxpayers to check the Unreconciled figure and revisit their data if it is not zero.
An unreconciled amount therefore indicates that the financial information entered into the Wealth Statement does not yet balance according to the IRIS reconciliation.
Why Is My Wealth Statement Not Reconciling?
If the unreconciled amount is not zero, do not simply insert a random figure somewhere to force the return to balance.
Instead, check the underlying data.
Common causes can include:
- Incorrect previous-year wealth
- Missing bank balance
- Missing asset
- Incorrect liability
- Personal expenses entered incorrectly
- Income entered incorrectly
- Genuine inflow not entered
- Genuine outflow omitted
- Asset purchase or disposal not reflected correctly
- Figures copied incorrectly from the previous year
- A receipt or expense entered in the wrong category
The objective is not merely to achieve a zero.
The objective is to achieve a zero using correct and explainable figures.
Example: Buying a Car During the Year
Suppose you buy a car during the tax year.
The purchase may increase the assets shown in your Wealth Statement.
But the reconciliation also needs to explain where the money came from.
Depending on the actual facts, the source might have been:
- Current-year savings
- Previous savings/cash
- Sale of another asset
- Bank financing
- A genuine loan
- Another legitimate source
You should report the actual transaction rather than creating an artificial source merely to reconcile the statement.
Example: Receiving a Gift
Suppose a family member genuinely gives you money and you use it to acquire an asset.
Your wealth may increase even though that amount did not come from your salary.
IRIS provides Gift as one of the possible reconciliation inflow categories.
However, the tax/legal treatment and documentation of a gift can depend on the facts.
Therefore, declaring an amount as a “gift” should never be used simply as a balancing figure.
What About Property, Vehicles and Other Assets?
Assets should be entered under the appropriate categories available in the current Wealth Statement.
FBR’s Wealth Statement instructions indicate that assets are generally valued at cost for Wealth Statement purposes.
Keep records supporting significant assets and transactions where appropriate.
If an asset was financed, the corresponding genuine outstanding liability may also be relevant.
Should Bank Accounts Be Included?
Bank balances form part of a person’s financial position and should be handled according to the applicable Wealth Statement fields.
The important figure is generally the relevant balance for the reporting date rather than simply the total amount that moved through the account during the year.
Do not confuse:
bank account balance
with
total deposits/transactions during the year.
They are different concepts.
Should Cash in Hand Be Declared?
Where a taxpayer genuinely holds cash that forms part of their wealth, it should be reported appropriately.
However, cash should not be inflated merely to make the Wealth Statement reconcile.
An unusually large cash balance that cannot be explained by the taxpayer’s financial history and available resources may create questions rather than solve them.
Use realistic, supportable figures.
Wealth Statement for a First-Time Filer
First-time filing can require additional care because there may be no immediately preceding Wealth Statement in IRIS to use as a reference.
FBR’s Wealth Statement instructions state that where a statement is being filed for the first time or covers more than one tax year, separate reconciliation of increases/decreases in wealth and sources/applications should be provided for each relevant year.
A first-time filer should therefore avoid inventing an opening financial position.
Prepare the historical figures carefully and obtain professional assistance if the taxpayer has substantial assets, businesses, property or unexplained differences.
If you are not yet registered with FBR, first see our NTN registration online in Pakistan guide.
Can a Wealth Statement Be Revised?
Yes, subject to the applicable conditions.
FBR’s current published guidance states that a Wealth Statement can be revised in IRIS before receipt of a notice under section 122(9) without filing an application seeking approval for revision.
This is different from FBR’s stated procedure for revising an Income Tax Return, where an application for revision is required before the revised return can be filed.
Revision should be used to correct a genuine omission or wrong statement—not as a substitute for reviewing figures carefully before initial submission.
Wealth Statement and Foreign Assets
Taxpayers with significant foreign income or assets should be particularly careful because additional reporting requirements can apply.
Section 116A, as currently reproduced by FBR, requires a foreign income and assets statement from a resident individual meeting specified thresholds, including foreign income of at least USD 10,000 or foreign assets valued at at least USD 100,000, subject to the law’s requirements.
This is a separate issue from simply completing ordinary Wealth Statement fields.
Taxpayers with foreign assets or income should consider professional advice where necessary.
Common Wealth Statement Mistakes
Some of the most important errors to avoid are:
- Entering assets at arbitrary figures
- Forgetting genuine liabilities
- Ignoring personal expenses
- Using the wrong previous-year net wealth
- Omitting a genuine inflow or outflow
- Treating every bank transaction as income
- Using fake gifts or loans to balance reconciliation
- Artificially increasing cash in hand
- Copying last year’s Wealth Statement without updating it
- Focusing only on making the unreconciled figure zero rather than ensuring the underlying information is correct
Remember:
A reconciled Wealth Statement should also be an accurate Wealth Statement.
How Do You Know the Wealth Statement Has Been Submitted?
FBR states that successful submission of the Income Tax Return and Wealth Statement in IRIS is confirmed when both forms move from the Draft folder to Completed Task.
Therefore, merely saving your work is not the same as successfully submitting it.
After filing, verify its status in IRIS.
Frequently Asked Questions
What is a Wealth Statement in Pakistan?
A Wealth Statement is a statement of assets and liabilities together with information used to explain the taxpayer’s financial position and changes in wealth.
Is Wealth Statement part of income tax return filing?
FBR’s current filing guidance states that completing an online Income Tax Return involves completing the Return of Income and Wealth Statement.
What should the unreconciled amount be?
The Unreconciled Amount should be zero for successful wealth reconciliation. FBR’s IRIS help specifically instructs users to revisit their figures if this amount is not zero.
Why does my Wealth Statement show an unreconciled amount?
It means the movement in your net wealth does not currently match the relevant inflows and outflows entered in the reconciliation. Review income, expenses, assets, liabilities and other genuine receipts/payments.
Should I add a fake gift or loan to make reconciliation zero?
No. Only genuine transactions should be declared. The purpose of reconciliation is to explain your actual financial position, not simply to produce a zero balance.
Are assets declared at market value?
FBR’s Wealth Statement instructions generally state that assets should be valued at cost. However, the current IRIS return may request additional information depending on the tax year, so follow the applicable current form and instructions.
Can I revise my Wealth Statement after filing?
FBR currently states that a Wealth Statement can be revised in IRIS before receipt of a notice under section 122(9), without first filing an application seeking approval for revision.
How do I file the complete income tax return?
See our step-by-step guide on filing an income tax return online through FBR IRIS.
Final Words
A Wealth Statement should tell a consistent financial story.
Your opening wealth, income and other genuine inflows, personal expenses and other outflows, liabilities, asset purchases and closing wealth should make sense when viewed together.
Do not approach reconciliation by asking:
“What number should I enter to make it zero?”
Instead ask:
“Which genuine financial transaction or figure have I missed or entered incorrectly?”
That approach produces a Wealth Statement that is not only reconciled in IRIS but is also much easier to explain from your records if questions arise later.
Before submission, review the figures carefully and confirm that the Unreconciled Amount is zero and that the underlying information is accurate.
Official FBR Sources
FBR – Completing Income Tax Return and Wealth Reconciliation
FBR IRIS 2.0 Portal and Wealth Statement Help
FBR – Revising Income Tax Return and Wealth Statement
FBR – Section 116A Foreign Income and Assets Statement
Disclaimer
This article is provided for general educational and informational purposes only and does not constitute tax, legal or professional advice. Wealth Statement requirements and the correct treatment of assets, liabilities, gifts, loans, foreign assets and other transactions depend on individual circumstances and applicable tax law. Always verify current requirements through FBR/IRIS or consult a qualified tax professional where necessary.