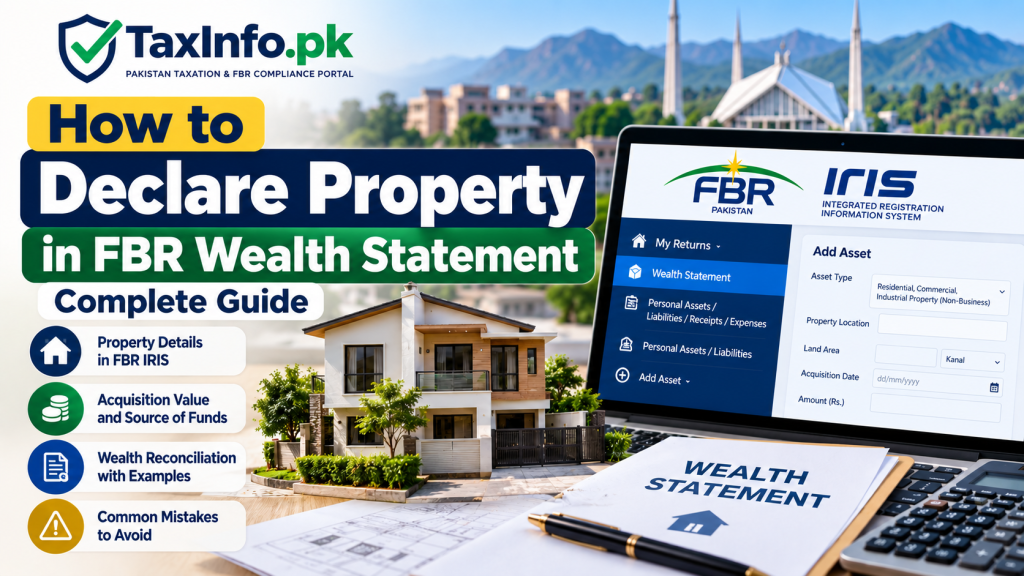
How to Declare Property in FBR Wealth Statement – Complete Guide
If you own a house, plot, apartment, shop, commercial property or agricultural land, it is important to Declare Property in Wealth Statement correctly while filing your income tax return through FBR IRIS.
Property is normally reported as an asset in the Wealth Statement. However, simply adding a property is not enough. Its acquisition details, amount, financing or source of funds, liabilities where applicable, and the resulting change in your net wealth should make sense together.
FBR’s official guidance explains that an online income tax return involves completing the Return of Income and Wealth Statement, and the Wealth Statement must reconcile before successful submission.
If you are unfamiliar with the overall process, first read our Wealth Statement in Pakistan – Complete FBR IRIS Guide.
This guide explains how to declare property in FBR IRIS, what property information to enter, how a property purchase affects wealth reconciliation, and the common mistakes taxpayers should avoid.
Table of Contents
Why Do You Need to Declare Property in Wealth Statement?
A Wealth Statement represents your financial position for the relevant tax year.
Depending on your circumstances, it can include assets such as:
- Residential property
- Commercial property
- Industrial property
- Agricultural property
- Motor vehicles
- Bank balances
- Cash
- Investments
- Business capital
- Other assets
It can also include liabilities and other information required for wealth reconciliation.
FBR’s official IRIS guidance provides separate asset categories for Agricultural Property and Residential, Commercial, Industrial Property (Non-Business).
Therefore, if you own a property that falls within the applicable Wealth Statement requirements, it should be reported under the appropriate category rather than being ignored simply because no rental income is being earned from it.
Property Ownership and Rental Income Are Different
Owning property and earning rental income from property are two separate matters for tax-return purposes.
For example, suppose you own a house worth Rs. 8,000,000 for Wealth Statement purposes and live in it yourself.
The house may still need to appear as an asset in your Wealth Statement even though it produces no rental income.
On the other hand, if you rent out the property, you may also have to report the relevant rental income under the applicable income-tax provisions.
For the income side, see our How to Declare Rental Income in FBR Tax Returns.
The basic distinction is:
| Item | Where It Is Relevant |
|---|---|
| Ownership of property | Wealth Statement |
| Rental income from property | Income Tax Return |
| Outstanding property financing/loan | Liability, where applicable |
| Purchase during the year | Wealth reconciliation |
| Sale/disposal during the year | Return/Wealth Statement treatment as applicable |
What Property Details Should You Keep Ready?
Before opening FBR IRIS, collect the information and documents relevant to the property.
Depending on the property and the fields displayed in the current IRIS form, useful information can include:
- Property type
- Property location/address
- Mauza, village or Chak number where applicable
- Union Council
- Tehsil
- District
- Division
- Province
- Country
- Land area
- Covered area where applicable
- Measurement unit
- Acquisition date
- Amount/value used for Wealth Statement purposes
- Purchase documents
- Evidence of payments
- Details of any genuine financing or loan
FBR’s IRIS help specifically shows fields relating to property location, land area, measurement unit and acquisition date when an appropriate property asset is added.
Keeping the underlying records ready makes the declaration much easier and reduces the risk of entering inconsistent information.
How to Declare Property in Wealth Statement
The exact appearance of IRIS can change, but FBR’s published guidance provides the general process for entering personal assets.
Step 1: Log In to FBR IRIS
Open the official FBR IRIS portal and log in using your credentials.
Make sure you are preparing the Wealth Statement for the correct tax year.
For example, Financial Year 2025–26 generally corresponds to Tax Year 2026 for a taxpayer following the normal tax year.
If this distinction is confusing, see our Tax Year vs Financial Year in Pakistan guide.
Step 2: Open the Wealth Statement
Open the relevant Income Tax Return and Wealth Statement for the tax year you are filing.
According to FBR’s official IRIS guidance, the Wealth Statement contains the section:
Personal Assets / Liabilities / Receipts / Expenses
Open this section and then select:
Personal Assets / Liabilities
This is where your property and other personal assets can be entered.
Step 3: Add a New Asset
Inside Personal Assets / Liabilities, use the + option to add an asset.
FBR’s IRIS help states that this opens a dialogue box where the taxpayer selects the appropriate options and provides the required asset information.
Fields marked with an asterisk are mandatory.
You should choose the asset category that actually describes your property.
Step 4: Select the Correct Property Type
IRIS guidance includes separate categories such as:
Agricultural Property
and
Residential, Commercial, Industrial Property (Non-Business)
Choose the category according to the actual nature and use of the property.
For example:
- Agricultural land → Agricultural Property
- Personal residential house → Residential Property
- Personal plot → appropriate residential/non-business property classification
- Personally owned shop → Commercial Property, where appropriate
- Personally owned industrial property → Industrial Property, where appropriate
Do not select an unrelated category merely because it makes data entry easier.
Step 5: Enter Property Location and Area
Enter the information requested by IRIS.
Depending on the property and current form, this may include details such as:
- Mauza / Village / Chak
- Union Council
- Tehsil
- District
- Division
- Province
- Country
- Land area
- Covered area
- Measurement unit
FBR’s IRIS guidance also explains that its search function can be used for location-related fields such as Union Council.
Enter the information according to your actual property records.
Step 6: Enter the Acquisition Date
Where IRIS asks for the acquisition date, enter the date on which you acquired the property according to the relevant records.
This becomes particularly important when the property was purchased during the current tax year because the acquisition can affect the movement in your wealth.
For example:
You did not own a plot on 30 June 2025.
You purchased it for Rs. 3,000,000 during Tax Year 2026.
The plot appears among your assets at the end of Tax Year 2026.
Your reconciliation must therefore be capable of explaining how that acquisition was funded.
Step 7: Enter the Property Amount
After adding the property record, enter the appropriate amount in the relevant Amount field.
This is an area where taxpayers often become confused between:
the amount at which an asset is carried in the Wealth Statement
and
the property’s current market or FBR valuation.
These concepts should not automatically be treated as the same thing.
Should You Enter Market Value of Property?
Do not automatically replace the Wealth Statement amount of an existing property with its latest market price merely because property prices have increased.
A particularly important recent example occurred in Tax Year 2025.
FBR initially introduced an Estimated Fair Market Value field for movable and immovable assets. It later officially removed that estimated market-value column from the return form.
FBR also clarified during that episode that those market-value entries were not being used for Wealth Statement reconciliation.
Therefore, do not rely on old screenshots or tutorials showing an estimated market-value field. Follow the fields appearing in the current IRIS form for the relevant tax year.
For FBR property valuation tables used for relevant property-tax purposes, consult the latest official valuation material rather than assuming that the valuation rate automatically replaces your Wealth Statement asset amount.
Example: Property Purchased During the Year
Suppose Ali had net assets of:
Previous year net assets: Rs. 4,000,000
During the current year, he purchases a plot for:
Rs. 2,500,000
He pays the entire amount from genuine accumulated/current financial resources that are properly reflected in his financial position.
At year-end, the plot becomes part of his assets.
However, entering Rs. 2,500,000 as property does not by itself explain the transaction.
IRIS also needs the overall Wealth Statement to reconcile.
The relevant question is:
Where did the Rs. 2,500,000 used to acquire the plot come from?
The answer depends on the taxpayer’s actual circumstances.
It could involve:
- Current-year savings
- Previously declared cash/bank resources
- Sale of another asset
- Genuine loan or financing
- Gift, where genuinely received and properly supportable
- Inheritance
- Foreign remittance, where applicable
- Another legitimate and explainable source
Never create an artificial source merely to make the reconciliation zero.
Example: Property Purchased Through Bank Financing
Suppose you acquire a property for:
Rs. 10,000,000
You pay:
Rs. 4,000,000 from your own resources
and finance:
Rs. 6,000,000 through a genuine outstanding bank facility.
The property asset and the genuine outstanding liability may both be relevant to your Wealth Statement.
In simplified terms:
Assets = Rs. 10,000,000
Outstanding Liability = Rs. 6,000,000
The resulting effect on net wealth is different from a situation where the entire Rs. 10,000,000 was paid from your own funds.
Actual entries should reflect the real financing arrangement and the amount genuinely outstanding at the relevant year-end.
Example: Property Bought in a Previous Year
Suppose you purchased a house several years ago and correctly declared it in your previous Wealth Statement.
If you still own the same property at the end of the current year, it should normally continue to be reflected in your assets consistently.
Do not remove an existing property simply because there was no transaction involving it during the current year.
Similarly, do not automatically increase its Wealth Statement amount every year merely because its market price has risen.
Consistency between tax years is important.
What If Property Was Received as a Gift?
Suppose a taxpayer genuinely receives property as a gift.
The transaction is different from buying property using salary savings.
The property may increase the taxpayer’s assets, while the corresponding genuine gift may be relevant when explaining the increase in wealth.
However, simply entering the word Gift does not establish that a genuine gift occurred or determine its legal or tax treatment.
Keep appropriate documentation and report the transaction according to its actual facts.
A fake gift should never be created simply to make the Wealth Statement reconcile.
What If Property Was Inherited?
An inherited property can also increase a taxpayer’s assets without being purchased from current salary or business income.
IRIS Wealth Statement reconciliation provides for different types of inflows, and inheritance may be relevant where genuinely applicable.
Keep supporting documents relating to the inheritance and ownership of the property.
The property should be declared according to the actual transaction and applicable reporting requirements.
What If You Sold a Property During the Year?
If a property shown in the previous Wealth Statement was sold during the current tax year, do not simply delete it and ignore the transaction.
The disposal may affect:
- Closing assets
- Cash or bank balance
- Relevant receipts/inflows
- Capital-gain or other tax treatment where applicable
- Wealth reconciliation
For example, if a property disappears from your assets but the sale proceeds are sitting in your bank account at year-end, the bank balance may increase correspondingly.
The entire financial transaction should make sense when the return and Wealth Statement are viewed together.
How Property Affects Wealth Reconciliation
This is one of the most important parts of declaring property.
FBR states that a Wealth Statement can only be successfully submitted when the movement between current-year and previous-year wealth corresponds with the relevant difference between inflows and outflows.
In simple terms:
Closing Net Wealth − Previous Net Wealth
should make sense when compared with:
Income / Other Genuine Inflows − Expenses / Other Outflows
The actual IRIS reconciliation contains specific fields, but this basic relationship helps explain why purchasing a major asset can create a reconciliation problem if its source is not properly reflected.
For a detailed explanation, read our complete Wealth Statement and reconciliation guide.
What Does Unreconciled Amount Mean?
FBR’s IRIS guidance explains that the difference between current-year wealth and previous-year wealth must correspond with the difference between inflows and outflows.
When the Wealth Statement reconciles correctly:
Unreconciled Amount = 0
Suppose you add a newly purchased property worth Rs. 5,000,000 but your reported financial information only explains Rs. 3,500,000 of that increase.
A reconciliation difference may arise.
The correct solution is not to invent Rs. 1,500,000 of cash, gift, loan or another receipt.
Instead, identify what genuinely funded the transaction and whether any legitimate asset, liability, income, receipt, expense or previous-year figure has been omitted or entered incorrectly.
Common Property Declaration Mistakes
1. Forgetting to Declare the Property
A taxpayer purchases property but fails to add it to the Wealth Statement.
This can create inconsistency between the taxpayer’s actual financial position and declared assets.
2. Declaring Rental Income but Not the Property
A taxpayer reports rent under Income from Property but forgets that the underlying property may also need to appear among their assets.
Rental income and property ownership are separate reporting concepts.
3. Using Current Market Price Every Year
An increase in the market price of a property does not mean you should automatically increase its Wealth Statement amount every year.
Follow the applicable Wealth Statement rules and current IRIS fields.
4. Ignoring the Source of Funds
A property worth millions of rupees is added to assets, but the taxpayer does not consider how the acquisition is reflected in wealth reconciliation.
This is one of the most important mistakes to avoid.
5. Adding a Fake Loan
Do not enter a fictitious loan simply to reduce net assets or eliminate an unreconciled amount.
Only genuine liabilities should be declared.
6. Using Cash in Hand as a Balancing Figure
Cash should represent your actual financial position.
If IRIS shows a Rs. 1,000,000 difference, simply adding Rs. 1,000,000 somewhere as cash does not establish that you actually possessed that cash.
7. Creating a Fake Gift
The same principle applies to gifts.
Only declare a gift where a genuine transaction occurred and the amount can be properly explained and supported.
8. Entering Property Under the Wrong Category
Agricultural property and residential/commercial/industrial non-business property are separately identified in FBR’s IRIS guidance.
Select the category that reflects the actual asset.
9. Ignoring Previous-Year Figures
Your current Wealth Statement is connected to your previous financial position.
An incorrect property amount carried forward from an earlier year can affect current reconciliation.
10. Using an Old IRIS Tutorial
FBR forms and electronic fields can change.
The Tax Year 2025 estimated-market-value issue is a good example. A field that appeared in an earlier version was subsequently removed.
Always follow the current IRIS form for the tax year being filed.
What If You Forgot to Declare Property in an Earlier Wealth Statement?
Do not automatically add the missing property to the current year without first determining when it was actually acquired and why it was absent from the earlier statement.
First identify:
- When the property was acquired.
- Which Wealth Statement should originally have contained it.
- How it was financed.
- Whether the relevant earlier Wealth Statement can legally and appropriately be revised.
- How any correction affects later years.
FBR currently provides a mechanism for revising a Wealth Statement subject to the applicable legal conditions.
For the complete procedure, see our How to Revise Wealth Statement in FBR IRIS guide.
This area deserves particular care.
In September 2026, FBR announced enforcement action involving taxpayers who allegedly revised old Wealth Statements to introduce previously undeclared cash, gold, prize bonds, properties and business capital. FBR stated that the explanation to section 116(3) restricts Wealth Statement revision after five years from the due date of the original return.
Therefore, old undeclared assets should not be “fixed” by creating fictitious historical cash or other unsupported sources.
Use genuine records and the legally available correction procedure.
Documents You Should Keep for Property
Depending on the transaction, useful records may include:
- Sale/purchase agreement
- Registry or conveyance documents
- Allotment or transfer documents
- Payment receipts
- Bank statements
- Pay orders or payment evidence
- Loan/financing agreement
- Outstanding financing statement
- Gift documentation where applicable
- Inheritance documents where applicable
- Evidence relating to property disposal
- Relevant tax-payment records
The exact documents depend on the property and transaction.
The objective is to be able to explain both ownership of the asset and the financial transaction behind it.
Final Checklist Before Submission
Before submitting your return, confirm that:
- The property has been entered under the correct asset category.
- Property location/details are accurate.
- Land/covered area is correctly entered where required.
- Acquisition date is correct.
- The amount entered is appropriate for Wealth Statement purposes.
- Genuine outstanding financing is correctly reflected where applicable.
- A current-year purchase has an explainable source of funds.
- A property sold during the year is correctly reflected in the overall financial position.
- Previous-year figures are consistent.
- Personal expenses and other relevant inflows/outflows are correctly reported.
- The Wealth Statement reconciliation is correct.
- The Unreconciled Amount is zero.
- No fake cash, loan, gift or other receipt has been inserted merely to force reconciliation.
After submission, you should also confirm that the relevant forms have actually moved from Draft to Completed Task.
Our How to Check Filed Income Tax Return in FBR IRIS guide explains how to verify this.
Frequently Asked Questions
How do I Declare Property in Wealth Statement?
Open the relevant Wealth Statement in FBR IRIS, go to Personal Assets / Liabilities / Receipts / Expenses, open Personal Assets / Liabilities, add a new asset, select the appropriate property category, enter the required property details and enter the applicable amount. Then review the Reconciliation of Net Assets before submission.
Is property declared in the Income Tax Return or Wealth Statement?
Ownership of the property is generally reflected in the Wealth Statement as an asset. Income generated by the property, such as rent, may separately need to be reported in the Income Tax Return.
Should I declare property at market value in FBR Wealth Statement?
Do not automatically substitute the latest market price for the amount carried in the Wealth Statement. Follow the applicable rules and fields of the current IRIS return. FBR removed the Estimated Fair Market Value column that had initially been introduced for Tax Year 2025.
What if my property value has increased?
A rise in market price does not by itself mean that you should automatically increase the amount of an existing property in your Wealth Statement. Follow the applicable Wealth Statement treatment and current IRIS requirements.
Do I have to declare a plot in my Wealth Statement?
Where the plot forms part of your reportable personal assets, it should be included under the appropriate property category according to its actual nature and the current IRIS fields.
Do I need to declare my own house if I do not receive rent?
Property ownership and rental income are separate issues. A property can be relevant to your Wealth Statement even when it generates no rental income.
What if I purchased property using a bank loan?
The property may be reported as an asset while the genuine outstanding financing may also be relevant as a liability. The entries should reflect the actual transaction and outstanding position at year-end.
What if my parents gifted me a property?
A genuinely gifted property can affect your assets and Wealth Statement reconciliation. Keep supporting documentation and report the transaction according to its actual facts rather than treating the gift as an arbitrary balancing figure.
What if I inherited property?
Inherited property may need to be included among your assets, while the genuine inheritance may also be relevant to explaining the increase in wealth. Keep the appropriate supporting records.
Why did my Unreconciled Amount increase after adding property?
A newly acquired property increases your assets. If the Wealth Statement does not adequately explain how the acquisition was funded, a reconciliation difference can arise. Check genuine income, savings, existing assets, financing, sale proceeds, gifts, inheritance, remittances and other relevant transactions according to your actual circumstances.
Can I add cash to make the Unreconciled Amount zero?
Cash should reflect actual cash held by the taxpayer. It should not be invented merely to eliminate a reconciliation difference.
Can I revise my Wealth Statement if I forgot a property?
FBR permits Wealth Statement revision subject to applicable legal conditions. Determine the correct acquisition year and the source of funds before making any revision. Do not create fictitious historical assets or receipts to force the figures to reconcile.
How do I file the complete income tax return after declaring property?
After completing the property and other Wealth Statement information, complete your Income Tax Return, review tax calculations, reconcile your Wealth Statement and submit the required forms. See our How to File Income Tax Return Online in Pakistan – FBR IRIS Guide for the complete process.
Final Words
Learning how to Declare Property in Wealth Statement is not simply about entering an address and an amount in FBR IRIS.
The property should fit logically into your overall financial position.
If you purchased property during the year, ask:
Where did the money come from?
If it was financed, check the genuine outstanding liability.
If it was gifted or inherited, report the actual transaction appropriately and retain supporting records.
If a previously declared property was sold, consider where the sale proceeds went and how the disposal affects your closing assets.
Most importantly, do not manipulate cash, gifts, loans or previous-year figures simply to make the Unreconciled Amount zero.
A properly prepared Wealth Statement should tell a consistent financial story from your previous-year wealth, current-year income and genuine inflows, expenses and outflows, property transactions, liabilities and closing assets.
Before submitting, review every major figure carefully, calculate the Reconciliation of Net Assets, and make sure the Unreconciled Amount is zero for the right reasons.