Missing a Withholding Tax Statement Due Date can create unnecessary compliance problems for a withholding agent in Pakistan. Similarly, filing a statement on time but entering an incorrect CNIC/NTN, tax section, transaction amount or withholding figure may require correction.
An important point is that there is not necessarily one universal deadline for every withholding statement. The applicable filing period and due date depend on the relevant provision, statement type and current FBR rules.
This guide explains how withholding tax statement due dates work, what can happen when a required statement is filed late, how late-filing penalties operate, and what to do if you discover an error after filing.
If you first need help with the actual filing process, read our step-by-step guide to filing a Withholding Tax Statement in FBR IRIS.
Table of Contents
What Is a Withholding Tax Statement?
A withholding tax statement reports prescribed information about tax deducted or collected by a withholding agent and the underlying transactions.
According to the official FBR Withholding Taxes guidance, the responsibility for withholding tax deduction at the applicable rate lies with the withholding agents prescribed for the relevant section.
FBR also states that Sections 165 and 165C of the Income Tax Ordinance, 2001 require relevant withholding agents to furnish withholding statements for the periods prescribed for that purpose.
If you are new to withholding tax, first read our Withholding Tax in Pakistan 2026-27 guide.
What Is the Withholding Tax Statement Due Date?
The correct Withholding Tax Statement Due Date depends on the statement and legal provision applicable to the withholding agent.
This distinction matters because taxpayers sometimes find old articles, screenshots or filing calendars online and assume that the same deadline applies to every current withholding statement.
That can be risky.
FBR currently publishes the Income Tax Rules, 2002 amended up to 15 September 2026.
Therefore, before relying on a deadline, confirm:
- the applicable withholding provision;
- statement type;
- reporting period;
- due date under the current law and rules;
- current IRIS requirements; and
- any relevant FBR notification or amendment.
Do not rely solely on a deadline remembered from a previous tax year.
Is Every Withholding Tax Statement Filed Quarterly?
You should not assume that every withholding statement follows exactly the same filing schedule without first identifying the applicable provision.
FBR describes Sections 165 and 165C withholding statements as statements required for the period prescribed for the purpose.
This makes it important to identify the actual statement and withholding-agent category before determining the deadline.
Where a quarterly statement applies, the relevant statutory schedule should be followed.
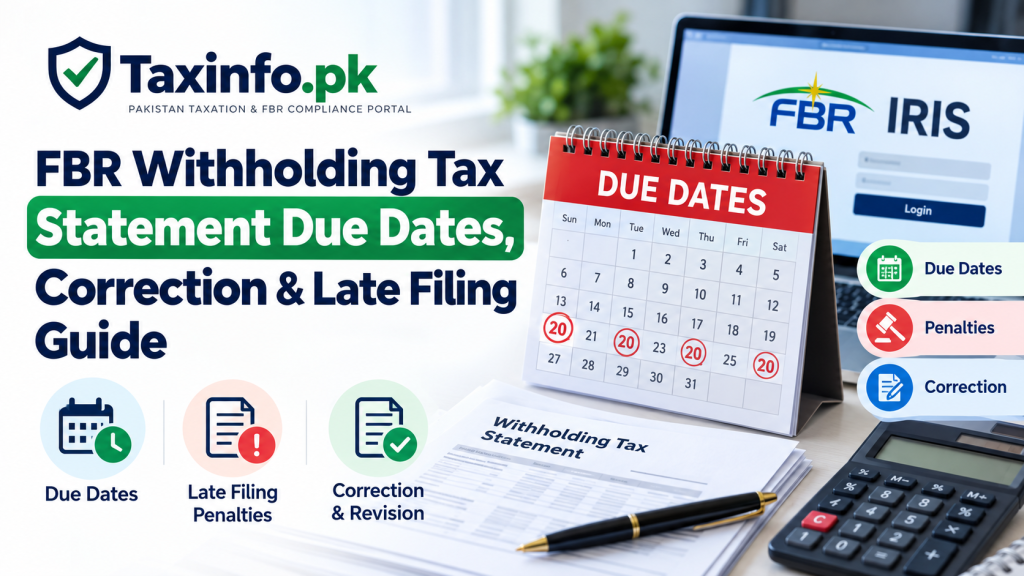
Quarterly Withholding Statement Due Dates
Current FBR rules provide quarterly reporting deadlines for specified withholding statements.
For example, under Rule 44 requirements applicable to specified courier/payment-intermediary reporting, the quarterly schedule is:
| Quarter Ending | Filing Due Date |
|---|---|
| 31 March | 20 April |
| 30 June | 20 July |
| 30 September | 20 October |
| 31 December | 20 January |
These dates should not automatically be applied to every withholding statement without checking the applicable provision.
The safest approach is to identify the statement that applies to you and verify its current prescribed period and deadline.
How to Check the Correct WHT Statement Due Date
Before filing, use the following process to determine the correct deadline.
1. Identify the Relevant Withholding Provision
First determine why tax is being deducted or collected.
Withholding tax can arise on transactions such as:
- salary;
- goods;
- services;
- contracts;
- rent;
- profit on debt;
- dividends;
- payments to non-residents; and
- other prescribed transactions.
The nature of the transaction helps determine the relevant withholding provision.
2. Identify the Correct Statement
Determine which withholding statement applies to your obligation.
Do not select a form merely because its description contains the words “withholding tax.”
If you need help with the actual IRIS filing process, follow our How to File Withholding Tax Statement in FBR IRIS guide.
3. Check the Current Income Tax Rules
FBR maintains the official Income Tax Rules, 2002 online.
Always use the latest available rules rather than relying on an old PDF saved on your computer.
4. Check FBR IRIS
When preparing the statement, carefully check the period and filing information available in the current system.
Use the official FBR IRIS Portal rather than an unofficial third-party website.
What Happens If You Miss the Withholding Tax Statement Due Date?
Missing a required filing deadline can expose the withholding agent to penalty provisions.
Section 182 of the Income Tax Ordinance contains penalties for various compliance defaults, including failure to furnish specified withholding statements within the applicable due date.
However, it is important to understand that the penalty treatment can depend on the circumstances.
In particular, FBR’s published Section 182 material distinguishes a case where withheld or collected tax was deposited on time and the statement was filed within 90 days from other cases.
Section 182 Penalty for Late Withholding Tax Statement
According to the official FBR Section 182 – Offences and Penalties, failure to furnish a statement required under the specified withholding-statement provisions within its due date can result in a penalty.
Two situations are particularly important.
Situation 1 — Tax Paid on Time and Statement Filed Within 90 Days
FBR’s published Section 182 table provides a penalty of:
Rs. 5,000
where:
- the person had already paid the tax collected or withheld within the due date for payment; and
- the statement is filed within 90 days from the due date for filing the statement.
Both conditions are important.
Therefore, the Rs.5,000 amount should not be interpreted as a universal fixed penalty for every late withholding statement.
Situation 2 — Other Cases
For other cases covered by the relevant Section from the due date, subject to a minimum penalty of Rs. 10,000.
The actual application of a penalty depends on the applicable provision and facts of the case.
A withholding agent should therefore not intentionally delay filing on the assumption that only a small fixed penalty will apply.
Example: Tax Paid on Time but Statement Filed Late
Suppose a withholding agent:
- correctly deducted the required tax;
- deposited the tax within its applicable payment deadline;
- but failed to file the required withholding statement by its due date.
If the relevant case falls within the Section 182 provision described above and the statement is filed within 90 days of its filing due date, the published Rs.5,000 penalty treatment may apply subject to the statutory conditions.
The important lesson is that depositing withholding tax and filing the withholding statement are separate compliance obligations.
Paying the tax does not automatically mean that the statement has been filed.
What If Withholding Tax Was Not Deposited on Time?
Failure to deposit deducted or collected tax can create a separate compliance issue.
FBR’s withholding-tax guidance states that withholding agents can be personally liable where the required amount is not deducted or where tax is deducted but not paid to the Federal Government, subject to the applicable provisions.
Therefore, withholding compliance should be viewed as a series of separate steps:
- determine whether withholding applies;
- deduct or collect the correct amount;
- deposit the tax within the applicable time;
- maintain proper records; and
- furnish the required withholding statement within its applicable deadline.
Completing one step does not necessarily satisfy the others.
How to File a Late Withholding Tax Statement
If the filing deadline has already passed, leaving the required statement unfiled does not resolve the issue.
First confirm:
- which statement was required;
- the relevant reporting period;
- whether withholding tax was deposited;
- when the tax was deposited;
- the amount involved;
- the applicable withholding section; and
- how much time has passed since the filing due date.
Then access the official FBR IRIS Portal and complete the applicable filing process using accurate records.
Our How to File Withholding Tax Statement in FBR IRIS – Step-by-Step Guide explains the filing workflow in detail.
Never change transaction dates or other information simply to make a late statement appear as though it was filed on time.
What If the Statement Was Filed on Time but Contains a Mistake?
Late filing and incorrect filing are different problems.
A statement can be submitted before the deadline but still contain an error such as:
- incorrect CNIC or NTN;
- incorrect transaction value;
- wrong withholding section;
- incorrect amount of tax;
- omitted transaction;
- duplicate transaction; or
- other incorrect reporting information.
If you discover an error after filing, determine whether the filed statement needs to be corrected or revised through the procedure applicable to that statement.
How to Correct or Revise a Withholding Tax Statement
If a filed withholding statement contains incorrect information, first identify exactly what needs to be corrected.
A practical approach is:
Identify the filed statement → identify the error → check the current revision option in IRIS → correct the relevant information → review the revised statement → complete the applicable submission process.
Do not change unrelated information merely because you are revising one part of the statement.
FBR’s systems and procedures can change, so always use the current IRIS workflow when correcting a previously filed statement.
Correction vs Revision — What’s the Difference?
Taxpayers sometimes use the words “correction” and “revision” interchangeably.
In practical terms:
Correction describes the information that needs to be fixed.
Revision generally refers to the process of submitting an amended version of an already filed statement through the available procedure.
The important issue is ensuring that materially incorrect information is not knowingly left unaddressed.
Incorrect CNIC or NTN in a Withholding Statement
CNIC and NTN errors should be taken seriously.
Taxpayer identification information helps associate withholding transactions with the relevant taxpayer.
An incorrect identification number may therefore cause information to be associated incorrectly or create validation and reconciliation problems.
Before filing or revising:
- verify the CNIC/NTN against your records;
- check the taxpayer’s name;
- confirm that the transaction belongs to that taxpayer; and
- avoid guessing an identification number.
If an incorrect CNIC or NTN has already been reported, check the current IRIS revision process for the relevant statement.
Wrong Withholding Tax Section
Selecting the wrong withholding section is another common filing error.
Different provisions can apply to:
- goods;
- services;
- contracts;
- rent;
- salary;
- profit on debt; and
- other payments.
The applicable section can affect both the tax rate and reporting treatment.
For a reader-friendly overview of current rates, see our FBR Withholding Tax Rates 2026-27 guide.
For official verification, use the FBR Withholding Tax Rate Card.
Incorrect Withholding Tax Amount
If the transaction information is correct but the tax amount is wrong, first determine why the error occurred.
Possible causes include:
- incorrect tax rate;
- wrong transaction amount;
- incorrect taxpayer status;
- wrong withholding section;
- calculation error; or
- incorrect data imported through a statement template.
Do not simply change the final tax figure without understanding the underlying cause.
For a broader explanation of withholding-tax treatment, read our Withholding Tax in Pakistan 2026-27 guide.
Check ATL Status Where Relevant
For some withholding provisions, taxpayer status can affect the applicable withholding rate.
Where ATL status is relevant to a transaction, confirm the taxpayer’s status and applicable legal provision before calculating the tax.
Our Active Taxpayer vs Non-Active Taxpayer in Pakistan guide explains the distinction and common tax differences.
Do not assume that every non-ATL transaction automatically attracts exactly twice the ATL rate. The current rate for the relevant provision should always be checked.
Late Filing vs Revision — Key Difference
Late filing, incorrect filing and late tax payment should not be treated as the same issue.
| Situation | Main Issue |
|---|---|
| Statement not filed by its due date | Late filing |
| Statement filed but information is incorrect | Correction / revision |
| Statement filed late and also contains errors | Both issues may need attention |
| Withheld tax not deposited within its payment deadline | Separate payment/default issue |
Fixing one issue does not necessarily resolve another.
For example, revising an incorrect statement does not automatically resolve a separate late-payment default.
How to Avoid Withholding Statement Problems
A simple compliance routine can prevent many errors.
Maintain a Withholding Register
Record relevant transactions throughout the reporting period rather than reconstructing everything immediately before filing.
Verify CNIC and NTN Details
Check identification information before entering or importing it into IRIS.
Identify the Correct Tax Section
Determine the actual nature of the transaction before selecting a withholding provision.
Use Current Withholding Rates
Tax rates can change from one tax year to another.
FBR currently provides a Tax Year 2027 Withholding Tax Rate Card, updated up to 30 June 2026 under the Finance Act 2026.
Use our FBR Withholding Tax Rates 2026-27 guide for an easier overview and the official FBR rate card for statutory verification.
Reconcile Tax Payments
Compare tax deducted or collected with the amounts actually deposited.
Check the Filing Period
Make sure you are preparing the correct statement for the correct period.
Do Not Wait Until the Last Day
IRIS validation issues, identification errors and data-import problems may take time to resolve.
Can FBR Extend a Withholding Tax Statement Due Date?
Tax deadlines can sometimes be affected by amendments, notifications, orders or other official measures.
However, taxpayers should not assume that an extension exists merely because FBR extended a deadline in an earlier period or for another filing obligation.
Unless an official current extension applies to your particular statement, work according to the normal applicable deadline.
Always verify deadline extensions through official FBR information rather than relying only on social-media posts or forwarded messages.
Why Old WHT Deadline Articles Can Be Misleading
Withholding reporting requirements have changed over time.
Reporting frequencies, statement formats, withholding categories and IRIS procedures can be amended.
For this reason, an old article may correctly describe the rules that existed when it was written but still be unsuitable for a current filing.
For current compliance, check:
- the latest Income Tax Ordinance;
- the latest Income Tax Rules;
- current FBR notifications where relevant;
- current IRIS requirements; and
- the statement applicable to your specific withholding obligation.
FBR currently lists the Income Tax Ordinance, 2001 amended up to 30 June 2026 and the Income Tax Rules, 2002 amended up to 15 September 2026.
Frequently Asked Questions
What is the Withholding Tax Statement Due Date in Pakistan?
There is not necessarily one universal due date that should be applied to every withholding statement without checking the relevant provision. The applicable reporting period and deadline depend on the statement and current legal requirements.
Are all withholding tax statements filed quarterly?
Do not assume that every withholding statement has exactly the same reporting frequency. Identify the applicable statement and check the current prescribed period.
What are the quarterly withholding statement dates where the current quarterly schedule applies?
For the specified Rule 44 quarterly reporting discussed above, the schedule is:
- quarter ending 31 March — 20 April;
- quarter ending 30 June — 20 July;
- quarter ending 30 September — 20 October; and
- quarter ending 31 December — 20 January.
Always verify that this schedule applies to your particular statement.
What happens if I file a withholding statement late?
Section 182 contains penalty provisions for failure to furnish specified withholding statements within their due date. The applicable treatment depends on the circumstances.
Is the late-filing penalty always Rs.5,000?
No.
FBR’s published Section 182 table provides the Rs.5,000 treatment where the required conditions are satisfied, including timely payment of the tax collected or withheld and filing the statement within 90 days of its filing due date.
What is the penalty in other cases?
For other cases covered by the relevant Section 182 entry, FBR’s published table provides a penalty of Rs.2,500 for each day of default from the due date, subject to a minimum penalty of Rs.10,000.
Can I file a withholding statement after its due date?
If a required statement has been missed, leaving it permanently unfiled does not resolve the compliance issue. Determine the applicable requirement and complete the filing using accurate records while considering the consequences of late filing.
Can I correct a withholding statement after submission?
Where a filed statement contains an error, check the current IRIS procedure for correction or revision applicable to that statement.
What if I entered the wrong CNIC or NTN?
Verify the correct taxpayer information and check the applicable revision procedure rather than knowingly leaving incorrect identification data in the filed statement.
Is depositing withholding tax enough if I do not file the statement?
No. Depositing withheld or collected tax and furnishing a required withholding statement are separate compliance obligations.
Where can I learn how to file a withholding statement?
Read our How to File Withholding Tax Statement in FBR IRIS – Step-by-Step Guide for the complete filing process.
Final Words
Understanding the correct Withholding Tax Statement Due Date is important because withholding compliance involves more than simply deducting tax.
A withholding agent should:
Identify the correct withholding provision → determine the applicable statement and period → deduct or collect the correct tax → deposit it within the applicable time → maintain accurate records → file the required statement within its deadline.
If a deadline has already been missed, further delay does not resolve the problem. Determine the correct filing requirement, reconcile your records and complete the applicable process.
If a statement was filed but contains incorrect information, distinguish the correction issue from late filing and use the current revision procedure where applicable.
For the actual filing process, continue with our complete Withholding Tax Statement filing guide.
For rates and transaction treatment, see our FBR Withholding Tax Rates 2026-27 guide and Withholding Tax in Pakistan guide, while using current official FBR material for statutory verification.