Withdrawing cash from a bank account may result in advance tax if the account holder is not appearing on the Active Taxpayers List (ATL). The Tax on Cash Withdrawal in Pakistan is therefore particularly important for people who have bank accounts but are not active taxpayers.
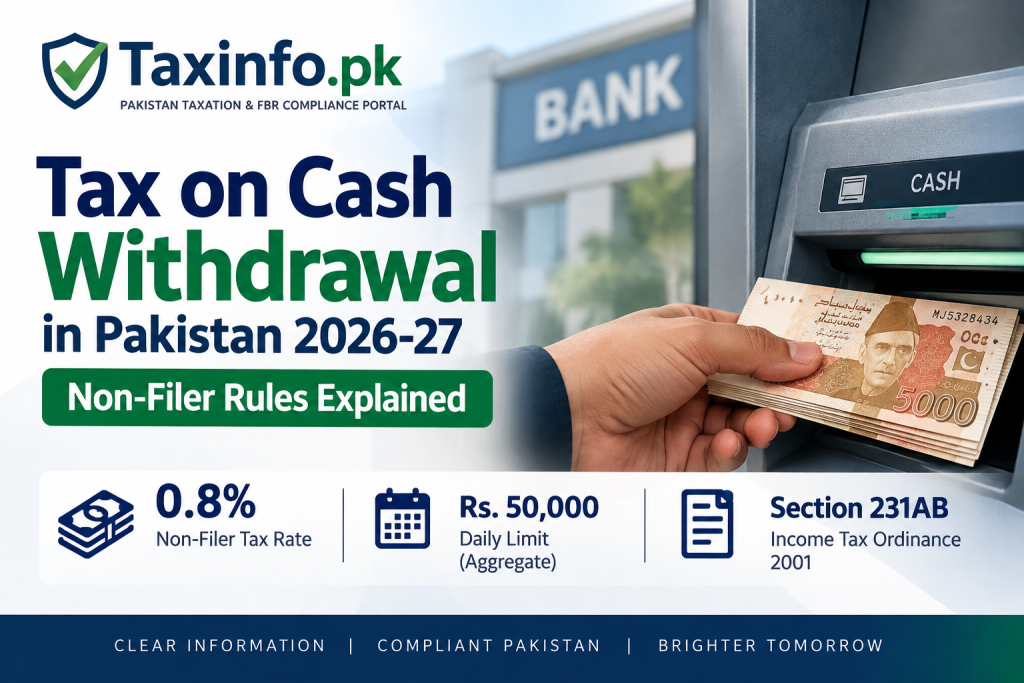
Under Section 231AB of the Income Tax Ordinance, 2001, a banking company is required to deduct advance adjustable tax from qualifying cash withdrawals made by a person whose name is not appearing in the ATL.
For 2026-27, the applicable rate is 0.8% where the aggregate cash withdrawals in a single day exceed Rs. 50,000.
This guide explains the current rate, daily threshold, calculation method, ATL implications and other important rules in simple terms.
Table of Contents
What Is Tax on Cash Withdrawal in Pakistan?
The Tax on Cash Withdrawal in Pakistan is an advance tax deducted by banks under Section 231AB of the Income Tax Ordinance, 2001.
It applies to a person:
- whose name is not appearing in the Active Taxpayers List (ATL); and
- whose aggregate cash withdrawals in a single day exceed Rs. 50,000.
The bank deducts the applicable tax when the conditions under Section 231AB are met.
FBR describes withholding taxes generally as advance payments of tax deducted when specified economic activities take place.
Cash Withdrawal Tax Rate for 2026-27
The applicable rate under Section 231AB is:
| Taxpayer Status | Cash Withdrawal Tax |
|---|---|
| Person appearing in ATL | Section 231AB tax does not apply |
| Person not appearing in ATL | 0.8% |
The relevant threshold is aggregate cash withdrawals exceeding Rs. 50,000 in a single day.
The 0.8% rate originated from an increase from the previous 0.6% rate, and the provision applies to persons not appearing in ATL.
What Is the Rs. 50,000 Daily Limit?
A particularly important part of Section 231AB is that the threshold is based on the aggregate cash withdrawals in a single day.
This means you should not look only at each individual withdrawal separately.
Example
Suppose a non-ATL person makes these cash withdrawals on the same day:
- First withdrawal: Rs. 30,000
- Second withdrawal: Rs. 25,000
- Total withdrawal during the day: Rs. 55,000
The aggregate withdrawal has exceeded Rs. 50,000.
Therefore, the transaction falls within the scope of Section 231AB.
This aggregate-single-day concept is expressly reflected in FBR’s explanation of the provision.
How Is Tax on Cash Withdrawal Calculated?
Once Section 231AB applies, the rate is 0.8% of the cash withdrawal amount.
For example, if a person not appearing in ATL withdraws:
Rs. 100,000
the tax calculation would be:
Rs. 100,000 × 0.8% = Rs. 800
The person would therefore face a tax deduction of Rs. 800 on the qualifying cash withdrawal.
More Examples
| Cash Withdrawal | 0.8% Tax |
|---|---|
| Rs. 60,000 | Rs. 480 |
| Rs. 100,000 | Rs. 800 |
| Rs. 200,000 | Rs. 1,600 |
| Rs. 500,000 | Rs. 4,000 |
| Rs. 1,000,000 | Rs. 8,000 |
These examples show why the Tax on Cash Withdrawal in Pakistan can become significant for people making large cash withdrawals while not appearing in ATL.
Enter your total daily cash withdrawal and taxpayer status to instantly estimate tax under Section 231AB.
Use Cash Withdrawal Tax Calculator →Does This Tax Apply to ATL/Filer Persons?
Section 231AB specifically targets a person whose name is not appearing in the Active Taxpayers List.
Therefore, if your name is appearing in ATL, this particular 0.8% cash-withdrawal tax under Section 231AB does not apply.
This is one of the practical benefits of maintaining active taxpayer status.
FBR also lists lower tax deduction on banking transactions, including cash withdrawals, among the benefits associated with ATL status.
If you are unsure about the difference between active and non-active taxpayers, read our guide:
Active Taxpayer vs Non-Active Taxpayer in Pakistan
Is the Rs. 50,000 Limit Per Transaction or Per Day?
It is based on the aggregate cash withdrawals in a single day, not merely on one individual transaction.
For example, splitting Rs. 60,000 into:
- Rs. 30,000 in the morning; and
- Rs. 30,000 later the same day
does not mean that each withdrawal is independently below the threshold for purposes of the daily aggregate.
Together, the withdrawals amount to Rs. 60,000 for that day.
The statutory explanation was specifically included to clarify that Rs. 50,000 refers to aggregate cash withdrawals in a single day.
Is Cash Withdrawal Tax Adjustable?
Yes. Section 231AB describes this deduction as advance adjustable tax.
This distinction is important.
An adjustable tax is generally taken into account against the taxpayer’s tax liability in accordance with the applicable income-tax rules, rather than automatically being treated as a final tax in every case.
Taxpayers should therefore maintain proper records of tax deducted by their banks.
FBR states that taxpayers can view withholding-tax information through their IRIS account, including through the Tax Payments area under MIS.
Can You Claim Excess Tax Back?
Because the deduction is adjustable, the amount may be taken into account when determining the taxpayer’s tax position.
Where a taxpayer ultimately has an eligible excess tax amount, the applicable refund procedure may become relevant.
For the complete process, see:
How to Claim Income Tax Refund from FBR
However, a refund is not automatic merely because tax was deducted from a cash withdrawal. Eligibility depends on the taxpayer’s overall tax position and applicable FBR rules.
How to Avoid Higher Tax on Cash Withdrawals Legally
The practical solution is not to try to structure withdrawals to circumvent the law. Instead, taxpayers should ensure their tax compliance and ATL status are properly maintained where applicable.
A person who is required to file an income tax return should file the return correctly and ensure that the relevant requirements for inclusion in ATL are fulfilled.
Our guides can help:
How to Become a Filer in Pakistan
How to File Income Tax Return Online in Pakistan
How to Check Your Tax Deduction in FBR IRIS
Taxpayers should periodically reconcile the withholding taxes deducted from their transactions with the information available in FBR’s system.
You can log in to the official FBR IRIS portal:
FBR explains that withholding-tax information under most relevant sections can be viewed through IRIS by accessing the Tax Payments area under MIS.
If you have difficulty accessing IRIS, see:
FBR IRIS Login, Forgot Password & Account Recovery
Why ATL Status Matters for Bank Customers
ATL status can affect several types of tax deductions—not just cash withdrawals.
FBR lists benefits of ATL status including reduced withholding-tax implications relating to banking transactions, property transactions, motor vehicles, dividends and other specified activities.
Therefore, people regularly carrying out taxable transactions should understand their filing and ATL status rather than considering cash-withdrawal tax in isolation.
Frequently Asked Questions
What is the tax on cash withdrawal in Pakistan for non-filers?
Under Section 231AB, a person whose name is not appearing in ATL is subject to 0.8% advance adjustable tax where aggregate cash withdrawals in a single day exceed Rs. 50,000.
Is there cash withdrawal tax for filers?
Section 231AB applies to a person whose name is not appearing in ATL. An ATL person is therefore outside this particular 0.8% deduction.
What happens if I withdraw exactly Rs. 50,000?
The statutory threshold refers to aggregate cash withdrawals in a day exceeding Rs. 50,000. Accordingly, exactly Rs. 50,000 does not exceed that threshold.
What if I withdraw more than Rs. 50,000 in several transactions?
The withdrawals are considered in aggregate for the day. Splitting the amount into multiple cash withdrawals on the same day does not change the daily aggregate test.
Is the cash withdrawal tax 0.6% or 0.8%?
The current rate is 0.8%. FBR’s official explanatory circular states that Finance Act 2025 increased the rate from 0.6% to 0.8%.
Final Words
Understanding the Tax on Cash Withdrawal in Pakistan is particularly important for bank customers who are not appearing in the Active Taxpayers List.
The key points are simple: Section 231AB applies a 0.8% advance adjustable tax where a non-ATL person’s aggregate cash withdrawals in a single day exceed Rs. 50,000.
Maintaining proper tax records, checking ATL status and filing required returns can help taxpayers manage their tax affairs correctly.
For the latest official withholding rates, taxpayers should also check FBR’s current Tax Year 2027 rate card, which FBR identifies as updated through 30 June 2026 under Finance Act 2026.
Disclaimer
This article is for general informational and educational purposes only and should not be considered professional tax or legal advice. Tax laws, rates, thresholds and FBR procedures may change from time to time. Although TaxInfo.pk aims to provide accurate and updated information, taxpayers should verify the latest requirements from the Federal Board of Revenue (FBR) or consult a qualified tax professional where necessary.