Advance Tax in Pakistan is a system under which eligible taxpayers pay part of their expected income tax during the tax year instead of waiting until the annual income tax return is filed.
For Tax Year 2027, Section 147 of the Income Tax Ordinance, 2001 governs the main advance-tax mechanism. Depending on the taxpayer type, advance tax may be payable in quarterly installments and is generally adjusted against the final tax liability for the relevant tax year.
However, Section 147 does not apply in exactly the same way to every taxpayer. Individuals, Associations of Persons (AOPs) and companies have different calculation rules, thresholds and payment dates.
This guide explains Advance Tax in Pakistan under Section 147, including who has to pay it, how quarterly installments are calculated, due dates for 2026-27, adjustment of taxes already paid, and what happens if advance tax is not paid on time.
Table of Contents
What Is Advance Tax in Pakistan?
Advance tax is essentially income tax paid during the tax year against the taxpayer’s expected annual tax liability.
Instead of requiring the entire tax amount to be paid when the annual return is filed, Section 147 requires qualifying taxpayers to discharge part of their liability during the year.
This is different from many forms of withholding tax where another person, such as a bank, employer or customer, deducts or collects tax from a transaction.
Under Section 147, the taxpayer may have a direct obligation to calculate and pay advance tax.
If you want to understand the broader distinction between tax deducted at source and other advance taxes, read our Withholding Tax in Pakistan – Complete Beginner’s Guide.
What Is Section 147 of the Income Tax Ordinance?
Section 147 of the Income Tax Ordinance, 2001 deals with advance tax paid by taxpayers.
Broadly, a taxpayer whose income was charged to tax for the latest tax year may become liable to pay advance tax for the current year, subject to the exclusions and conditions contained in Section 147.
The current official law can be checked through the FBR Income Tax Ordinance, which FBR currently publishes in a version amended up to 30 June 2026.
The purpose is straightforward: where a taxpayer is expected to have a tax liability during the year, part of that liability is collected progressively rather than entirely at year-end.
Who Has to Pay Advance Tax under Section 147?
Section 147 can apply to:
- Individuals meeting the applicable threshold and conditions
- Associations of Persons (AOPs)
- Partnership firms falling within the AOP framework
- Companies
- Other taxpayers covered by the provision
However, merely earning income does not automatically mean that every person has a separate quarterly Section 147 liability.
The nature of the income, previous assessed income, taxpayer type, taxes already deducted or collected and other provisions of the Income Tax Ordinance must also be considered.
Special Rule for Individuals
For an individual, Section 147 does not apply where the individual’s latest assessed taxable income, after excluding the income specified in Section 147(1), is less than:
Rs. 1,000,000
Therefore, the Rs. 1 million threshold is particularly important when determining whether an individual falls within the quarterly advance-tax mechanism.
This threshold should not be confused with the general income tax slabs or return-filing requirements. They are separate concepts.
Does Section 147 Apply to Salary Income?
Salary income subject to deduction of tax at source under Section 149 is excluded from the normal Section 147 advance-tax mechanism.
For a salaried employee, the employer generally deducts income tax from salary under Section 149 during the year.
Therefore, a person who only earns salary should not automatically assume that he or she must separately pay quarterly advance tax under Section 147.
However, the position may be different where the person also has other taxable income to which Section 147 applies.
For the latest salary rates, see our Income Tax Rates for Salaried Persons 2026-27.
Income Excluded from the Normal Section 147 Mechanism
Section 147 contains specific exclusions.
These include, among others:
- Income chargeable under Sections 5, 6 and 7
- Salary income subject to tax deduction under Section 149
- Certain income from which tax has been collected or deducted and for which no tax credit is available because of Section 168(3)
This distinction matters because Pakistan’s tax system contains many taxes described as “advance tax,” but they do not all represent a quarterly payment under Section 147.
For example, advance tax may also be collected when purchasing or selling property, withdrawing cash in certain circumstances, or carrying out other transactions.
You can review current transaction-based deductions in our FBR Withholding Tax Rates 2026-27 guide.
Advance Tax Due Dates for Individuals in 2026-27
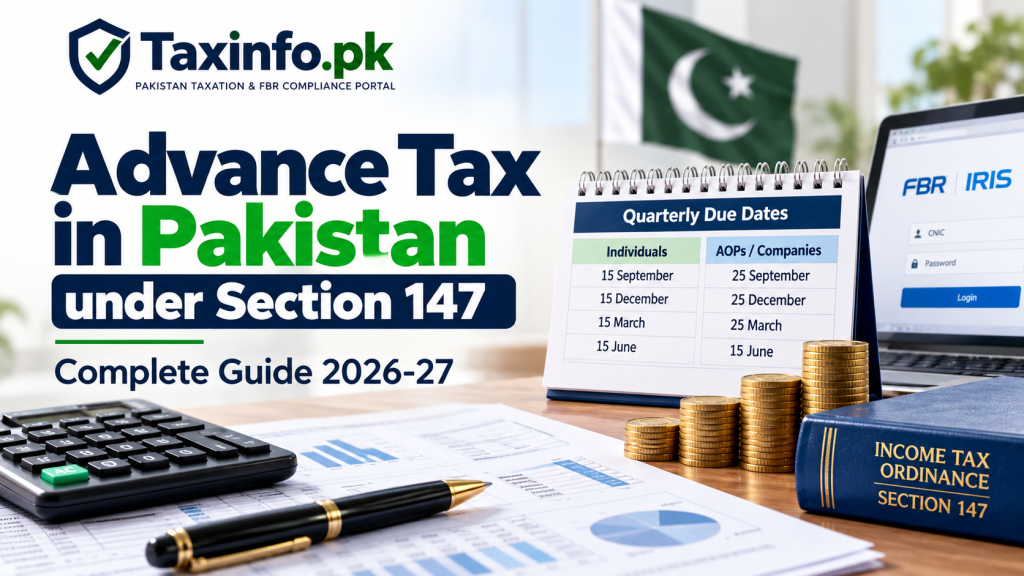
An individual who is required to pay advance tax under Section 147 generally follows these quarterly deadlines:
| Quarter | Due Date |
|---|---|
| September Quarter | 15 September |
| December Quarter | 15 December |
| March Quarter | 15 March |
| June Quarter | 15 June |
For the normal Tax Year 2027 period, this means the installments fall during the financial year running from 1 July 2026 to 30 June 2027.
If you are confused about the relationship between a financial year and an FBR tax year, see our Tax Year vs Financial Year in Pakistan guide.
Advance Tax Due Dates for AOPs and Companies
Associations of Persons and companies have different deadlines for the first three quarters.
| Quarter | AOP / Company Due Date |
|---|---|
| September Quarter | 25 September |
| December Quarter | 25 December |
| March Quarter | 25 March |
| June Quarter | 15 June |
This distinction is important.
An individual normally works with the 15th, while an AOP or company generally has until the 25th for the September, December and March quarters. The June installment is due by 15 June.
Taxpayers should always confirm the current statutory deadline before payment, particularly where FBR announces any general or specific extension.
How Is Advance Tax Calculated for an Individual?
For an individual falling within Section 147, the quarterly advance tax is generally calculated using:
(A ÷ 4) − B
Where:
A = tax assessed to the taxpayer for the latest tax year
B = qualifying tax paid during the relevant quarter for which tax credit is allowed under Section 168, excluding salary tax deducted under Section 149.
In simple terms, the previous assessed annual tax is divided into four parts and the qualifying adjustable tax already paid during the quarter is taken into account.
Example: Individual Advance Tax Calculation
Suppose an individual’s tax assessed for the latest tax year is:
Rs. 400,000
One-fourth of that amount is:
Rs. 400,000 ÷ 4 = Rs. 100,000
Assume qualifying adjustable tax already paid during the quarter is:
Rs. 25,000
The simplified Section 147 calculation becomes:
Rs. 100,000 − Rs. 25,000 = Rs. 75,000
Therefore, the estimated advance tax payable for that quarter would be:
Rs. 75,000
This is only an illustration. The actual calculation must be based on the taxpayer’s assessment, income composition and tax credits available under the applicable law.
Advance Tax Formula for AOPs and Companies
For an Association of Persons or a company, the calculation is turnover-based.
The general Section 147 formula is:
(A × B ÷ C) − D
Where:
A = taxpayer’s turnover for the relevant quarter
B = tax assessed to the taxpayer for the latest tax year
C = taxpayer’s turnover for the latest tax year
D = tax paid during the quarter for which tax credit is allowed under Section 168
This method effectively uses the relationship between the taxpayer’s previous tax assessment and turnover and applies it to current-quarter turnover.
Example: AOP or Company
Suppose a business has:
Latest tax year turnover: Rs. 40,000,000
Tax assessed for latest tax year: Rs. 800,000
Current quarter turnover: Rs. 12,000,000
Qualifying adjustable tax already paid during the quarter: Rs. 50,000
Calculation:
Rs. 12,000,000 × Rs. 800,000 ÷ Rs. 40,000,000
= Rs. 240,000
Less qualifying tax already paid:
Rs. 240,000 − Rs. 50,000
= Rs. 190,000
The simplified advance-tax liability for the quarter would therefore be:
Rs. 190,000
What If Quarterly Turnover Is Not Available?
Section 147 also addresses situations where an AOP or company fails to provide quarterly turnover or that turnover is not known.
In that situation, the relevant turnover figure for the formula may be taken as:
One-fourth of 120% of the turnover of the latest tax year for which a return has been filed.
For example, if the latest reported turnover is:
Rs. 100 million
120% of turnover:
Rs. 120 million
One-fourth:
Rs. 30 million
That figure may then be used as the quarterly turnover component for the statutory calculation.
This makes accurate turnover records particularly important for businesses subject to advance tax.
What If Current-Year Income Is Higher Than Last Year?
A taxpayer’s current-year position may differ substantially from the previous year.
Section 147 contains an estimation mechanism for taxpayers covered by the turnover-based calculation.
Where the estimated tax payable for the current tax year is likely to exceed the amount otherwise payable under the statutory calculation, an estimate of the current-year tax liability may have to be furnished to the Commissioner in accordance with Section 147.
The estimated liability is then paid after taking into account amounts already paid.
For businesses experiencing rapid growth, this is important because simply relying on last year’s figures may not always discharge the current advance-tax obligation.
What If Current-Year Income or Profit Is Lower?
The reverse situation can also arise.
A business may have experienced:
- Lower sales
- Reduced profit margins
- Business closure or slowdown
- Exceptional expenses
- A significant fall in taxable income
- Other genuine commercial changes
Section 147 contains provisions dealing with estimates of lower tax liability as well.
However, a taxpayer should not simply reduce or stop quarterly payments without following the applicable statutory procedure.
Where a lower estimate is furnished, the taxpayer should be able to support it with reliable accounts, turnover information, tax calculations and other relevant records. The Commissioner may examine the estimate in accordance with the law.
Are Taxes Already Deducted or Collected Adjustable?
Tax already deducted or collected during the year can be important when calculating the amount still payable.
Section 147 formulas recognize qualifying tax for which a tax credit is available under Section 168.
This prevents the taxpayer from simply paying the same adjustable liability twice.
However, not every withholding or collection automatically produces an adjustable credit. Some taxes may have a different treatment under the Income Tax Ordinance.
Our Withholding Tax in Pakistan guide explains the difference between adjustable and other forms of withholding tax.
Is Advance Tax a Separate or Extra Tax?
Generally, Section 147 advance tax is not meant to be an additional tax on top of the taxpayer’s final income tax liability.
It is an advance payment toward the relevant year’s tax.
Section 147 provides for credit of advance tax against the tax payable for the tax year.
For example:
Final income tax liability: Rs. 500,000
Advance tax already paid: Rs. 350,000
Remaining tax, before considering any other applicable credits or adjustments:
Rs. 150,000
Conversely, if allowable advance tax credits exceed the final liability, the excess may potentially form part of the taxpayer’s refundable tax position, subject to the Income Tax Ordinance and FBR procedures.
Advance Tax vs Withholding Tax – What Is the Difference?
These terms are often confused.
Advance tax under Section 147 generally involves quarterly payments made toward the taxpayer’s expected income tax liability.
Withholding tax, on the other hand, is commonly deducted or collected at source when a specified payment or transaction takes place.
For example:
- Employer deducting tax from salary
- Bank deducting applicable tax
- Tax deducted from certain payments for goods or services
- Advance tax collected on property transactions
- Tax collected on certain cash withdrawals
Some withholding taxes are adjustable against the final liability, while the treatment of others depends on the relevant provision.
Therefore, the words “advance tax” should not automatically be interpreted as Section 147 tax.
Examples of Other Advance Taxes in Pakistan
Pakistan’s Income Tax Ordinance contains several transaction-based advance taxes.
For example, property buyers and sellers may encounter advance tax under Sections 236K and 236C.
Our FBR Tax on Property in Pakistan 2026-27 guide explains the current buyer and seller rules.
Similarly, Section 231AB can apply to qualifying cash withdrawals by persons whose names are not appearing on the Active Taxpayers List.
See our Tax on Cash Withdrawal in Pakistan 2026-27 guide for details.
These transaction taxes should not be confused with the quarterly Section 147 calculation.
Quick Tool – Estimate Your Income Tax
Before estimating your advance-tax position, it can be useful to understand your expected annual income tax liability.
Use the TaxInfo.pk Tax Calculators to estimate income tax using current Tax Year 2027 rules.
The calculators can help you understand your basic annual tax position, but Section 147 liability should still be determined separately according to the statutory formula, previous assessment, current turnover and qualifying tax credits.
How to Pay Advance Tax to FBR
Tax payments can be made through FBR’s prescribed payment system.
A typical process involves:
- Log in to FBR IRIS using your credentials.
- Open the relevant payment or e-payment section.
- Create the required payment slip for Income Tax.
- Select the correct tax year.
- Enter the relevant payment details and amount.
- Generate the payment reference/PSID where applicable.
- Pay through an available banking channel.
- Keep the payment evidence and verify the resulting CPR.
FBR explains that a Computerized Payment Receipt (CPR) is generated after payment and is generally reflected in IRIS after the payment is processed.
Taxpayers can review FBR’s official Pay Income Tax guidance for the current payment process.
Always check that the correct tax year, payment type and amount have been selected before completing the payment.
Why Is the CPR Important?
The Computerized Payment Receipt is evidence that the tax payment has been deposited.
You should retain the CPR because it can be useful when:
- Preparing the annual income tax return
- Reconciling tax payments
- Checking tax credits
- Responding to an FBR query
- Verifying whether a payment has been properly reflected in IRIS
A payment should not simply be assumed to have been correctly credited because money has left the bank account. The tax record and CPR should also be checked.
What Happens If Advance Tax Is Not Paid on Time?
Failure to pay advance tax when required can have financial consequences.
Under Section 205, default surcharge can apply where a person fails to pay advance tax under Section 147 within the prescribed time.
Accordingly, ignoring quarterly advance-tax obligations can increase the taxpayer’s eventual cost even though the underlying advance tax itself is adjustable against the relevant annual liability.
Businesses and other taxpayers subject to Section 147 should therefore review their liability before each applicable quarterly deadline rather than waiting until the annual return is filed.
Does Advance Tax Appear in the Annual Income Tax Return?
Yes. Advance tax paid during the year is relevant when determining the taxpayer’s final tax position.
At return-filing stage, the taxpayer generally reconciles:
- Final taxable income
- Tax liability
- Tax deducted or collected at source
- Advance tax paid
- Other allowable tax credits
- Remaining tax payable or refundable amount
This is one reason why accurate CPRs and withholding records should be maintained throughout the year.
Advance Tax and Tax Year 2027
For a taxpayer following Pakistan’s normal tax year:
1 July 2026 to 30 June 2027 = Tax Year 2027
Therefore, quarterly advance-tax payments falling within this period generally relate to Tax Year 2027.
Taxpayers should be careful not to select an incorrect tax year when generating payment details in IRIS.
Common Mistakes to Avoid
Several mistakes can create problems when dealing with Advance Tax in Pakistan.
1. Assuming Every Advance Tax Is Section 147 Tax
Tax collected on property, cash withdrawals or other transactions may be described as advance tax but arises under different sections.
2. Using the Wrong Due Date
Individuals and AOPs/companies do not have identical deadlines.
3. Ignoring Tax Already Paid
Qualifying adjustable taxes can affect the amount payable under the Section 147 formula.
4. Using an Old Tax Assessment Without Reviewing Current Business Conditions
Current-year income or turnover may have changed significantly.
5. Reducing Advance Tax Without Following the Required Estimate Procedure
A genuine decline in income does not mean a taxpayer should simply ignore the statutory payment mechanism.
6. Selecting the Wrong Tax Year
For the normal financial period 2026-27, the corresponding FBR tax year is generally Tax Year 2027.
7. Not Keeping the CPR
Always retain and verify evidence of payment.
Frequently Asked Questions
What is Advance Tax in Pakistan?
Advance tax is tax paid during the tax year toward a taxpayer’s expected final income tax liability. Section 147 contains the main quarterly advance-tax mechanism for qualifying taxpayers.
What is Section 147 in Pakistan?
Section 147 of the Income Tax Ordinance, 2001 governs advance tax paid by taxpayers and provides rules for liability, calculation, estimates, quarterly payment dates and adjustment.
What is the Section 147 threshold for an individual?
Under the current law, Section 147 does not apply to an individual where the latest assessed taxable income, after the exclusions specified by the section, is less than Rs. 1 million.
What are the advance tax due dates for individuals?
The normal quarterly dates are:
15 September, 15 December, 15 March and 15 June.
What are the advance tax due dates for companies and AOPs?
The normal quarterly dates are:
25 September, 25 December, 25 March and 15 June.
How is advance tax calculated for an individual?
The general formula is:
(A ÷ 4) − B
where A represents tax assessed for the latest tax year and B represents qualifying tax already paid during the quarter, subject to the rules of Section 147.
How is advance tax calculated for a company or AOP?
The general formula is:
(A × B ÷ C) − D
It takes into account current-quarter turnover, tax assessed for the latest tax year, previous-year turnover and qualifying tax already paid during the quarter.
Is advance tax refundable?
Advance tax is generally credited against the taxpayer’s tax liability for the relevant tax year. Where allowable tax credits exceed the final liability, an excess credit may potentially result in a refundable position subject to the applicable provisions and FBR refund procedure.
Is salary tax the same as Section 147 advance tax?
No. Salary income subject to deduction under Section 149 is excluded from the normal Section 147 mechanism. Employers generally deduct salary tax at source.
Can advance tax already deducted elsewhere be adjusted?
Qualifying tax for which credit is allowed under Section 168 can affect the Section 147 calculation. The exact treatment depends on the section under which the tax was deducted or collected.
What happens if I do not pay advance tax?
Where Section 147 requires payment and the taxpayer fails to pay within the prescribed time, default surcharge and other consequences under the Income Tax Ordinance may apply.
Final Words
Advance Tax in Pakistan under Section 147 is designed to spread qualifying taxpayers’ income tax payments across the tax year instead of leaving the entire liability until annual return filing.
For individuals, the Rs. 1 million latest assessed taxable income threshold is an important starting point. Individuals generally follow quarterly dates of 15 September, 15 December, 15 March and 15 June.
AOPs and companies generally pay by 25 September, 25 December, 25 March and 15 June, and their calculation is linked to turnover and the tax assessed for the latest tax year.
Most importantly, advance tax should not automatically be treated as an additional tax. Qualifying payments are taken into account when the taxpayer’s final income tax liability is determined.
Because Section 147 calculations can depend on previous assessments, current turnover, withholding credits, estimates, minimum tax, super tax and the taxpayer’s particular circumstances, businesses with significant liabilities should reconcile their figures before every quarterly deadline.
For the latest statutory position, taxpayers should always refer to the Federal Board of Revenue and the current Income Tax Ordinance, 2001.